

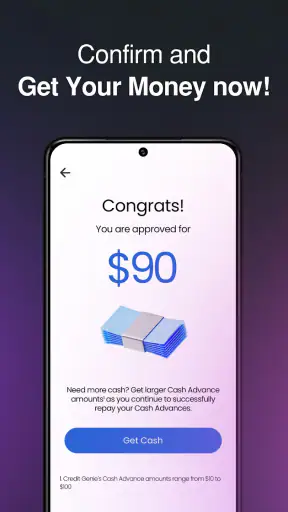
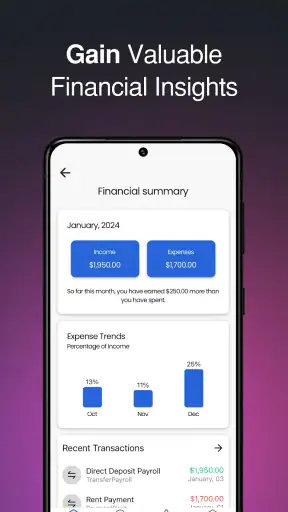
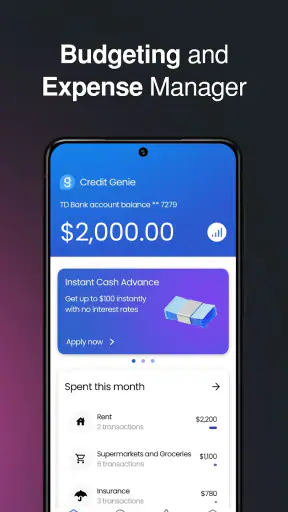
When I first opened Credit Genie, I approached it less like a traditional banking app and more like a financial starting point for people who want help making sense of credit. That distinction matters. It is a free finance app from Creditly Corp, aimed at everyday users rather than accountants or professional money managers. My impression is that its strongest value appears when you begin with a vague concern—“How can I understand my credit better?”—and want one place to organize the next step.
The app is available to an Everyone audience, runs on devices using Android 10 or later, and has reached over one million installs. Its current version is 3.5.0. Those details make it feel like an established consumer tool rather than a small experiment, while the 4.7 average from around eighty-three thousand ratings suggests that many users find the basic experience useful. I would still treat those figures as a sign to investigate, not as a guarantee that every person will get the same result.
From financial uncertainty to a clearer next step
Starting with the problem you actually have
A common mistake with finance apps is opening one without knowing what you want from it. That usually leads to a crowded dashboard, a few alarming numbers, and no practical decision. Credit Genie works better when I begin with a clear situation: I am preparing to apply for credit, trying to understand why an application may be difficult, or simply attempting to build a more disciplined view of my financial position.
That starting condition changes how useful the app feels. If I only want to check a balance or move money between accounts, a bank’s own app is usually the more direct choice. If I want a full household budget with detailed categories, recurring transactions, and long-term reporting, a dedicated budgeting service may be stronger. Credit Genie makes more sense in the space between those options, where credit awareness and practical guidance matter more than advanced bookkeeping.
I also appreciate that the app’s store summary presents it as a broad money app, while its short description identifies it as “Credit Genie.” In practice, I would not interpret that as a replacement for every financial service on my phone. I see it as a focused companion for credit-related decisions, with a wider money-management feel around that central purpose.
Moving through the first setup
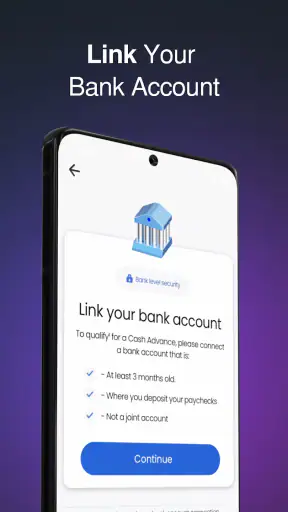
The first useful habit is to slow down during setup instead of tapping through every screen. Finance apps often ask for information that affects what they can show or recommend, so I would read each request and consider whether the benefit is worth the handoff. I would also make sure I am using the official Creditly Corp application and a secure device before entering sensitive information.
My practical advice is to begin with one goal. For example, if I am checking my readiness before applying for a new credit product, I would keep that purpose in mind as I move through the app. A narrow goal makes the later information easier to interpret and prevents me from treating every suggestion as equally important.
This is also where expectations should be realistic. A finance app can organize information and make decisions easier to think about, but it cannot remove the uncertainty involved in approval decisions. I would use Credit Genie to prepare and compare my options, not as a promise that a lender will accept an application or that a particular financial outcome will follow.
Turning information into an action plan
Once the initial information is available, the important step is not staring at a score or a recommendation. I try to translate what I see into a small action plan. That might mean reviewing a credit-related detail, deciding whether to wait before applying, or identifying a money habit that deserves attention. The app is more useful when it helps me answer “What should I do next?” rather than merely “What number am I looking at?”
One non-obvious advantage of this approach is that it reduces impulsive applications. People often apply for several products because they are unsure which one fits, then discover that the process itself can complicate their planning. I would use the app as a pause button: gather the relevant information, write down the reason for the application, and only then decide whether to continue elsewhere.
Another useful workflow is to separate observation from action. I would first record what the app is showing, then check whether the information matches what I already know from my financial accounts or documents. Only after that comparison would I act. This simple two-stage habit helps prevent a rushed response to an unfamiliar figure or an automated suggestion.
Understanding the handoffs between services
Credit Genie is not the entire financial journey. At some point, information or decisions may need to move to a bank, lender, card provider, or another financial service. That handoff is where many users misunderstand what an app can do. A helpful screen inside Credit Genie does not mean the receiving institution uses the same information, evaluates applications in the same way, or offers identical terms.
I would therefore treat the app as the preparation desk, not the final authority. Before accepting any offer or submitting an application outside it, I would read the destination service’s own terms, check the repayment details, and confirm whether the product matches my original goal. This is especially important when a recommendation looks convenient but solves a different problem from the one I started with.
The handoff also creates a record-keeping issue. I would save important details from any external application separately, including the date, the product considered, and the reason I applied. That makes it easier to understand my own decisions later and keeps the app from becoming the only place where my financial history exists.
For people who share financial responsibilities with a partner or family member, the handoff deserves extra care. I would not assume that showing someone a screen gives them the complete context. We would discuss the underlying decision together and verify details in the relevant account or provider. Credit Genie can support the conversation, but it should not replace it.
What the result looks like in daily life
Imagine that I am planning a major purchase and wondering whether applying for credit now is sensible. I open Credit Genie, review the information available to me, and use the app to frame the question more clearly. Instead of immediately submitting an application, I compare the situation with my budget, decide what I can comfortably manage, and identify what needs checking with the provider. The outcome is not a magical approval; it is a more deliberate decision.
That is where I think the app can earn a regular place on a phone. It can turn a vague worry into a repeatable routine: check the current picture, identify the next action, verify important details, and only then hand the decision to the appropriate financial institution. The routine is simple, but it is more valuable than a dashboard that I open once and forget.
Another realistic use is preparing for a conversation with a lender or financial adviser. I can use the app to organize the questions I want answered, then take those questions to the provider. This prevents me from confusing a general explanation with personalized financial advice. The app helps me arrive better prepared, while the provider remains responsible for explaining its own products and requirements.
For someone who is rebuilding financial confidence, that structure may be more important than advanced tools. The app gives the user a place to begin, but the user still has to verify, compare, and follow through. The strongest result is better decision discipline, not a shortcut around financial responsibility.
Where the flow becomes less comfortable
The first limitation is that a broad money-app identity can create wider expectations than the credit-focused name suggests. If I want detailed spending analytics, investment research, tax preparation, or a complete banking replacement, I would look elsewhere. Credit Genie may sit comfortably alongside those tools, but I would not choose it as the only app for every financial task.
The second limitation is interpretive. Credit information can feel authoritative even when I do not fully understand how it was produced or what it means for a particular application. I would avoid making a major decision based on one screen alone. The app can make information easier to approach, but I still need to read the lender’s conditions and consider my own ability to repay.
There is also a natural friction whenever a workflow crosses from an app into an outside service. I may need to repeat information, compare different terminology, or leave Credit Genie to complete the next stage. That is not necessarily a defect in this particular app; it is a reality of financial services. Still, users expecting a single uninterrupted journey may find the transition less smooth than the opening experience.
I would also skip it if my main requirement is a highly specialized tool. A person who wants granular envelope budgeting, business accounting, investment portfolio analysis, or direct control over bank transactions should choose software built specifically for that job. Credit Genie is better suited to a consumer who wants credit-related orientation and a manageable path from concern to action.
Who will get the most from it
I think the app is a good fit for a first-time credit user, someone preparing for a financial application, or anyone who wants a clearer routine around credit decisions without paying for the starting point. Its free price removes an obvious barrier to trying it, and the Everyone content rating makes it approachable for a broad audience.
It is also useful for people who tend to react too quickly to financial offers. By placing a review step before the external application, it encourages a little distance between seeing an option and accepting it. I would especially recommend that workflow to users who have previously applied without checking whether the product matched their budget or objective.
On the other hand, experienced users may find the app too general if they already have a carefully built system for monitoring credit and managing money. In that case, adding another dashboard could create duplication rather than clarity. The right test is simple: after using it, do I make decisions more calmly and keep better track of what I need to do? If not, another tool may fit my routine better.
My final experience with Credit Genie
After using Credit Genie as a step-by-step companion rather than a complete financial replacement, I found its appeal easier to define. It is not most valuable when I expect it to perform every money task. It is most valuable when I need help moving from uncertainty to a sensible next action, then handing that action to the correct bank, lender, or service.
Creditly Corp has positioned the app in a practical part of the finance category: accessible enough for everyday users, focused enough to support credit-related planning, and established enough to have more than nine thousand reviews alongside its broad rating base. I would still verify important information independently and keep expectations grounded, especially before making a borrowing decision.
My recommendation is therefore conditional but positive. Try Credit Genie if you want a free way to organize your thinking around credit and you are willing to do the final checking yourself. Skip it if you need a full bank replacement, advanced budgeting, or professional financial analysis. Used with that boundary in mind, it can turn a confusing financial moment into a clearer workflow: start with the problem, review the information, question the handoff, and act only when the result makes sense for you.


